When More Revenue Means Less Profit: Natalia Zacharin on the Economics of a Service Business
An accounting firm can be overwhelmed with client work and still be unable to afford the experienced hire needed to relieve the pressure. That contradiction is worth examining before demand is treated as proof that the business is ready to expand, because an overflowing workload can signal several very different things: strong market demand, inadequate pricing, an inefficient delivery model, or a founder who has been quietly subsidizing the company with her own time.
When those conditions persist, another client adds obligations before it adds meaningful financial room. The founder can keep the arrangement functioning by working longer hours, taking on more of the delivery herself, or delaying investments the company actually needs, but eventually the economics have to stand on their own. Once someone else must be paid to perform the work, growth exposes a question that a full calendar cannot answer: does the business generate enough value to deliver what it has promised without depending on the owner’s continued overextension?
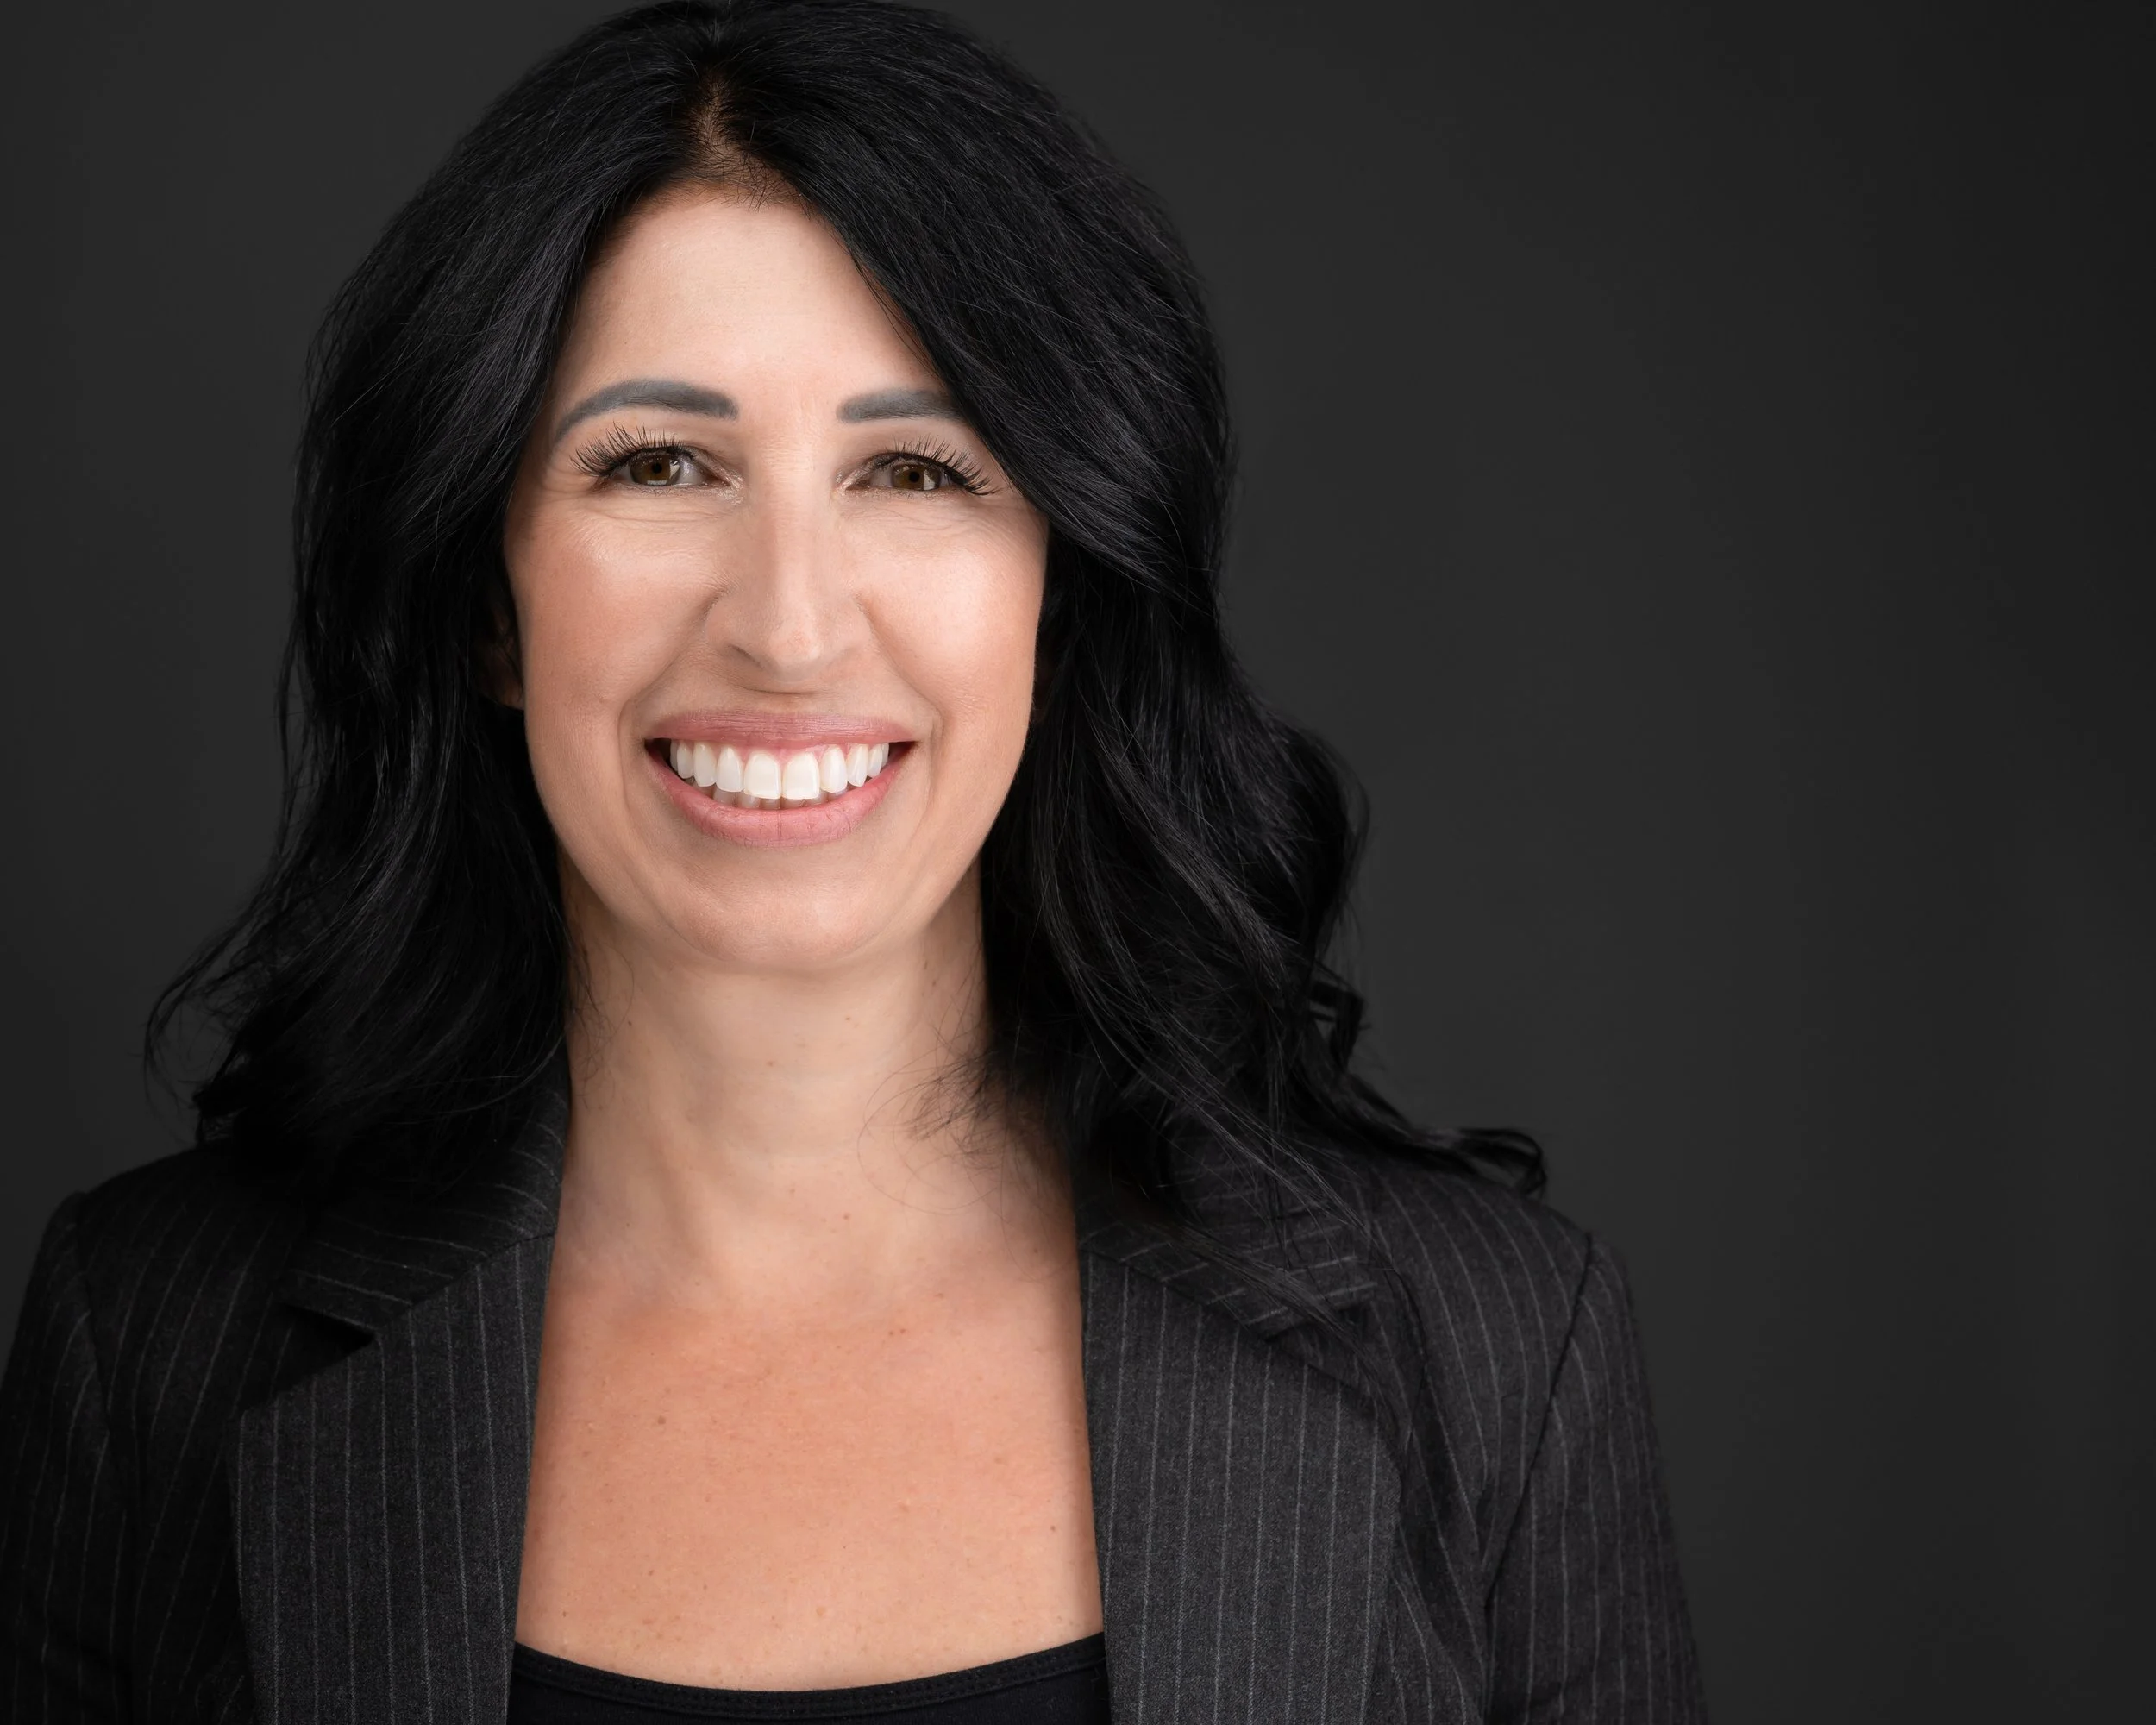
Natalia Zacharin confronted that question while building Zacharin Consulting, her accounting and fractional CFO firm. Following divorce and significant financial setbacks, the former invoicing clerk began finding bookkeeping clients in 2019, taught herself the work, and committed to the business full time during the month she turned 50. She went on to build a multimillion dollar firm recognized by the Inc. 5000, but what makes her experience particularly useful is her willingness to examine the decisions that made that growth harder than it needed to be.
Her story connects several decisions founders often treat as separate conversations. Pricing determines what the company can afford to deliver, hiring determines whether that delivery can happen without constant founder intervention, and forecasting tests whether the business can sustain the commitments created by both. Financial information, in that sense, is not merely a record of growth after it happens; used well, it becomes part of deciding whether that growth is economically worth pursuing.
Underpricing Becomes a Problem the Entire Company Has to Carry
As Natalia’s workload increased, she recognized that her pricing did not support the help she needed and doubled her rates for new clients. She left existing client pricing unchanged because she was afraid of losing them, and even her new rates were difficult to hold during sales conversations. She describes quoting a fee, becoming uncomfortable with the silence, and beginning to explain or reduce the price before the prospect had raised an objection.
“It’s also hard not to decrease your value and your pricing because you’re getting a no.”
The consequence of that behavior extended well beyond the sales call. If a fee does not cover the work required to serve the client properly, the difference has to be absorbed somewhere, whether through the founder’s time, thinner margins, less experienced staffing, postponed investment, or eventually a lower standard of service. A founder who repeatedly discounts without changing the scope may therefore be making an operating commitment she has never fully costed, even when each individual concession seems manageable.
Natalia recalls substantially underquoting one prospect who described a struggling business, only to discover after beginning the engagement that the company had roughly $1 million sitting in its bank account. That balance did not determine what the client should have been charged, but it exposed how much Natalia had assumed before evaluating the work. She had allowed the story she heard about the business to influence the price rather than allowing the scope, complexity, and requirements of the engagement to determine it.
That distinction matters in professional services, where empathy can easily become entangled with economics. A founder may deliberately choose to make an accommodation, restructure a scope, or help a client through a difficult period, but that is different from reflexively reducing the fee because she feels uncomfortable asking for the price the work requires. The issue is not whether generosity belongs in business. The issue is whether the founder understands who ultimately absorbs its cost.
For an accounting firm, the answer is especially concrete. The records still have to be reviewed, the transactions reconciled, the financial statements made accurate, and the client supported. If the price does not cover that work, the company has not eliminated the cost; it has simply moved it somewhere less visible.
That is why Natalia’s first hiring problem was inseparable from her pricing problem.
A Hire Creates Leverage Only When Responsibility Actually Moves
When Natalia hired her first employee, she approached the decision cautiously. She brought in someone part time and hourly who had experience with desktop accounting software but needed substantial training in QuickBooks Online, which meant Natalia spent significant time teaching rather than immediately gaining capacity.
“There was no relief for me. There was just more work because I had to train her.”
Looking back, Natalia believes that hiring someone with more experience could have allowed her to transfer meaningful responsibility sooner and build the company faster. That does not mean developing a less experienced employee is inherently a poor decision; it means the organization needs enough capacity to make that development possible. A person hired to provide immediate relief should be evaluated differently from someone the company expects to train into greater responsibility over time.
The relevant calculation therefore extends beyond salary or hourly rate. A less expensive employee may require more supervision, more review, and more founder involvement, while a more expensive hire may be capable of taking ownership much sooner. The true question is not simply what the person costs, but what responsibility actually leaves the founder’s desk once that person arrives.
Natalia’s experience also illustrates why quality has to be built into the economics of the service rather than treated as something the founder personally guarantees forever. At Zacharin Consulting, she describes using controller level review, including CPA level oversight, because accuracy is part of what the firm promises its clients. That level of quality requires a staffing structure the pricing can support; it cannot depend indefinitely on the founder stepping back into every account whenever something becomes complicated.
This is where hiring and pricing become part of the same operating model. If the company cannot charge enough to employ the level of talent required to deliver the promised service, the problem is not simply recruiting. If every new employee creates additional work for the founder without transferring authority or accountability, the problem is not simply headcount. The business may be growing in size while remaining structurally dependent on the person who started it.
Accurate Books Matter Most When They Change the Next Decision
Natalia’s approach to learning accounting helps explain the service she eventually built. When she entered a transaction, she would examine what changed elsewhere in the financial statements, sometimes deleting and reentering the item so she could understand the relationship between the numbers. She was not simply teaching herself how to record financial activity; she was teaching herself how the business moved through its financial statements.
That distinction later surfaced in conversations with clients. They wanted accurate bookkeeping, but they also wanted to know what they were supposed to do with the information once they had it. In 2021, Natalia added fractional CFO services, which required her to learn forecasting, projections, and the forward looking work necessary to help business owners make decisions rather than merely review history.
Her distinction among the financial roles is straightforward. A bookkeeper records and reconciles what happened, while a controller brings greater technical oversight and helps ensure the accounting is reliable. A CFO uses that accurate information to examine where the company is headed and how decisions made today could change that direction.
“It’s not where you are now. It’s where you’re headed.”
For a growing company, that shift changes the purpose of financial information. The question surrounding a new hire is no longer simply whether there is enough money in the bank to make payroll this month, but what happens to cash over the next six, nine, or twelve months once compensation and the broader cost of the decision are considered. An investment can be examined the same way, not as an isolated expense but as a commitment whose consequences unfold over time.
Forecasting does not remove uncertainty, nor does Natalia present it as a prediction that will unfold exactly as modeled. Its value is that it forces the founder to make assumptions visible while there is still time to respond to them. If revenue arrives more slowly than expected, if a hire takes longer to become productive, or if expenses increase more quickly than planned, the founder can examine the implications before those changes become an urgent cash problem.
That is a fundamentally different use of financial information. The numbers stop serving primarily as confirmation of what has already happened and begin informing choices that have not yet been made.
Understand the Cash Shortage Before Taking on More Debt
The distinction between historical reporting and forward looking financial management becomes particularly important when a company begins running short of cash. Natalia describes businesses taking repeated loans without correcting the operating problem that caused the shortage, including one client who eventually arrived at her firm carrying 20 loans.
She distinguishes between borrowing to acquire something that can help the business generate additional revenue, such as equipment, and borrowing because the company cannot make payroll. In the second situation, the need for cash may be immediate, but obtaining the money does not explain why the shortage occurred or whether the company will find itself in the same position again.
“A loan because you don’t have enough cash because you can’t make payroll is a different story.”
Natalia begins by examining the business itself, including pricing, productivity, operating inefficiencies, overspending, owner distributions, and money being redirected elsewhere. Each possibility requires a different response, which is why diagnosis matters. If a service company is consistently charging too little for the work it performs, another infusion of cash does nothing to change the economics of the next client engagement.
The same scrutiny becomes necessary when revenue is rising because top line expansion can conceal declining financial performance. Natalia describes seeing businesses at $4 million in revenue that were less profitable than they had been at $1 million because expenses had increased even faster than sales. The owner now carries more employees, greater complexity, additional liability, and considerably more work without receiving a proportionate financial return from the larger company.
That does not mean every temporary reduction in profitability signals a poor growth decision. A founder may intentionally hire ahead of demand or make investments that reduce short term profit while preparing the company for a larger opportunity. What matters is whether the financial impact is understood and deliberate, rather than discovered only after the costs have become embedded in the business.
This is where Natalia’s arguments about forecasting, cash flow, pricing, and hiring converge. Growth creates commitments before the founder knows with certainty how much return those commitments will generate, which makes it increasingly important to understand what the company can absorb before another employee is hired, another loan is signed, or another layer of overhead becomes permanent.
Revenue Is Evidence of Demand, Not Proof of a Healthy Business
Taken together, Natalia’s experience suggests a more rigorous way to evaluate the next stage of a service business. Before pursuing another revenue milestone, the founder needs to understand what that growth requires in delivery capacity, technical oversight, management attention, and cash, because selling the work is only the beginning of the economic equation.
A useful analysis starts with the work the company is already performing. Which engagements generate enough margin to support the people required to deliver them? Where is the founder quietly contributing hours that never appear in the cost of service? Which responsibilities would genuinely transfer with the next hire, and which would continue returning to the owner? Once those questions become visible, forecasting can test what happens when the business makes its next move.
The appropriate staffing ratios, margins, and level of financial support will vary by company, so Natalia’s experience is more valuable as a way of thinking than as a set of universal benchmarks. Her own firm taught her that a pricing decision can determine whether an experienced hire is affordable, the quality of that hire can determine whether the founder gains meaningful capacity, and the financial forecast can determine whether the company is prepared to carry the resulting commitment.
That is the larger argument running through her story. Revenue is evidence that customers are willing to buy, but it is not proof that the business model becomes stronger with every additional sale. A company can grow quickly while becoming less profitable, more dependent on its founder, and increasingly vulnerable to cash pressure if the economics underneath that growth are never examined.
A better measure is whether each stage of growth improves the quality of the company itself: whether the work generates enough margin to support the people delivering it, whether the founder is transferring responsibility rather than merely accumulating employees, whether cash is being created by the operating model rather than repeatedly borrowed to compensate for it, and whether financial information gives leadership enough visibility to make consequential decisions before those decisions become expensive to reverse.
Natalia’s full conversation with Cristy and Aggie on the Badass Women in Business Podcast goes deeper into the sales conversations she wishes she had handled differently, the mistakes surrounding her first hire, the distinction between bookkeeping, controller, and CFO level work, and the challenge of maintaining financial and service standards while scaling a team. Follow the show on Apple Podcasts, Spotify, or YouTube, and continue exploring the larger conversation about ownership, money, leadership, and growth through the proveHER Blogcast.
To learn more about Natalia’s work, visit Zacharin Consulting, explore the firm’s business resources, connect with Natalia on LinkedIn, or visit the resource page she created for Badass Women in Business listeners.
For founders building toward greater profit, ownership, and enterprise value, the question is not simply whether the business can grow. It is whether the company can afford the way it is growing, and whether each new stage is creating a business that is financially stronger, operationally more capable, and less dependent on the founder than the one that came before it.